Saturday, October 11, 2014

The Privy Counselor

I would advise against it, My Lord
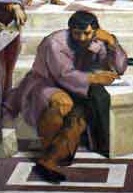
Diego Velasquez, Portrait of Pedro de Barberana, 1631
No! I am not Prince Hamlet, nor was meant to be;
Am an attendant lord, one that will do
To swell a progress, start a scene or two,
Advise the prince; no doubt, an easy tool,
Deferential, glad to be of use,
Politic, cautious, and meticulous;
Full of high sentence, but a bit obtuse;
At times, indeed, almost ridiculous—
Almost, at times, the Fool.


— T.S. Eliot, “The Love Song of J. Alfred Prufrock”

So The Blackstone Group decided yesterday to spin off its advisory business and merge it with Paul Taubman’s advisory “kiosk.” This is just the sort of relatively trivial exercise—the advisory group in question accounted for only 6.4% of Blackstone’s revenue and 2.1% of its economic income—that sets financial journalists’ and Wall Street pundits’ heads to nodding and chins to wagging, based almost entirely on the undeniable fact that Blackstone is big and important in the financial ecosystem.1 But I must pop my head up from my hidey hole, if only briefly, to take issue with some of the hasty conclusions being drawn here. I promise to withdraw swiftly and silently at the conclusion.

First, I must disagree with William Alden that Blackstone’s actions somehow contradict prevailing wisdom on Wall Street:
For decades, it has been a deeply held belief among many of Wall Street’s giants that a multiplicity of business lines is superior to a more streamlined model.
No, the conventional wisdom on Wall Street is and always has been quite simple: do whatever makes the most money. This is actually quite a sensible, beautiful, adaptable, and flexible business strategy. Sometimes, in fact, it does encourage executives to add business lines to their firms when they believe those businesses will add revenue and profit synergies to their existing business while being profitable in their own right (i.e., earning a return on top of paying for the people, assets, and financing costs they require). But more often than not it entails creating new products or services within existing business lines (like derivatives within capital markets operations), or just hiring a bunch of clowns who can cover an industry or execute a kind of business you do not already perform. (A “business line” in my industry is frequently little more than a handful of guys with business cards and a budget.) Often, as in the current environment, it encourages senior executives to discard unprofitable business lines, assets, or personnel by shutting them down, selling them, or just firing the unprofitable clowns because they can’t make money anymore or regulators are forcing you to get rid of unapproved activities.

Certainly there is a sensitivity among senior executives in finance to the benefits of maintaining a portfolio of complementary business lines, wherein secular and cyclical variations in the fortunes of certain lines can offset the different variations of others, and often there is a corollary fondness for the diversification accomplished through sheer size alone (usually by executives of big firms, natch). But both these considerations take a back seat to the short-, intermediate-, and long-run profit contributions, both direct and indirect, by the business lines in question to the mother ship. You can suckle at the corporate teat for a little while in my business while you wait for conditions to turn, but patience in the Executive Suite runs out pretty quickly if you can’t pull your own weight over the intermediate and long term. And notice I wrote the business lines must be complementary: if they don’t have the ability to contribute revenue and profit synergies to other business lines or the firm overall, their chance of staying within the fold long term—whether at GigantoBank or Two Guys and a Phone, LLC—are pretty darn slim.2

Enforcing this strategy from the other direction, by the way, are the self-interested considerations of the personnel who run the business lines in question. If they calculate belonging to the mother ship does not enhance their own intermediate- and long-term earnings and personal wealth generation prospects (via subsidy in bad times and better pay in good times than they could achieve elsewhere), they have absolutely no hesitation to jump ship for sunnier shores. From the top of the firm to the bottom, very few successful people on Wall Street value their job title and business card more than the contents of their paycheck, and most of us act accordingly. Besides, managing a multiplicity of business lines is hard. Even Wall Streeters know we are crap at management.

* * *

So I think it’s fair to take Blackstone at their word when they say they are divesting their advisory business due to structural conflicts with their core asset management businesses. In other words, not only was the advisory business not contributing any meaningful profit or revenue to the main group (q.v. supra), but also belonging to Blackstone was throttling the advisory group’s growth and profit opportunities. One can see this clearly in their results, where the Restructuring group has advised on the lion’s share of the unit’s business this year, $32.4 billion worth of deals, versus the regular advisory group’s relatively paltry $4 billion. This makes sense, since restructuring advisory (think bankruptcy, turnarounds, and workouts) is its own special business, with a different set of clients (failing companies, creditor groups, distressed investors), revenue model (hefty monthly retainers versus deal success fees), advisors (lots of ex-lawyers with sharp elbows and fierce manners), and business cycles (naturally, they tend to do well when everyone else is flat on their backs). They should normally have few conflicts with Blackstone’s core asset management businesses, most of which tend to invest in healthy companies or assets. The major exception cited in the articles—their inability to advise Lehman on its bankruptcy because Blackstone’s real estate division wanted to bid on its assets—is the killer exception that proves both the rule and the magnitude of the potential conflict.

Given that conditions are booming in regular M&A markets, the lackluster performance of Blackstone’s corporate advisory business is telling. Because Blackstone is so big and so active in principal investing across private equity, real estate, securities, and other asset classes, they must constantly show up on one side or another of potential transactions which its advisory group would like to get hired for. Such direct conflicts will usually put the kibosh on Blackstone’s advisors getting hired, or at least severely limit their alternatives. And even if no direct conflicts obtain, many corporate clients and virtually all competing private equity firms and principal investors are no doubt reluctant to hire Steve Schwarzman’s trained killers to give them highly sensitive financial and strategic advice. I can’t help but think this goes double for the third leg of Blackstone’s advisory stool, which helps raise money for—wait for it—other asset managers.

The point, in other words, is that Blackstone divesting its advisory business has nothing to do with bucking a nonexistent trend on Wall Street to add business lines like barnacles on a freighter. Instead, it has everything to do with dumping business lines that add no value, subtract value, or fail to realize their own value due to inherent negative synergies resulting from persistent structural conflicts of interest with the parent company. In other words, it is business as usual.

* * *

However, and for the very same reasons, Schwarzman pulling the ripcord on his M&A bankers does not signal the start of an industry-wide trend of divesting advisory groups by integrated investment banks. For one thing, big integrated investment banks with sales and trading, securities underwriting, and corporate advisory practices like the C-suite access top M&A and industry coverage bankers give them. Because they talk to the CEO, the CFO, and occasionally the Board of Directors, they have access to a level of decision making at corporate clients that the debt capital markets bankers and derivatives structurers do not. (They tend to talk to Treasurers or their finance staff.) This means they can get access to bigger, more profitable debt and derivatives deals and valuable, profitable product to pump into the insatiable maw of their huge trading machines. Profitable equity underwritings are also CEO- and Board-level prizes to give, and M&A deals are just icing on a cake that does not require meaningful capital to be put at risk.

M&A and corporate finance bankers like belonging to big integrated investment banks, too, when things work as they should. For one thing, it gives them more deals and ideas to talk about with their clients than just the usual who-should-buy-whom rigmarole. For another, it allows them to deepen and institutionalize their firm’s relationship with important clients by establishing multiple touch points and ongoing dialogues between subject matter experts within the bank and counterparts at the client. For a third, having equity research analysts who cover their clients and target industries gives them an entrée and a credibility with clients they do not know, and a capability to underwrite profitable equity business for those they do.

But most importantly, having M&A and industry bankers gives integrated investment banks an excuse to deliver ideas, industry and client insight, and all-important deal flow to the biggest-paying class of clients on Wall Street: private equity firms. While it is well known that private equity firms do not like paying M&A advisors for advice—usually because, rightly or wrongly, they think they know at least as much or more as bankers do about companies, deal-doing, and opportunities—they absolutely love paying investment banks to supply and arrange leveraged loans and high yield debt to finance buyouts of target companies. And banks love this too, because it is both huge and hugely profitable business. PE firms are usually happy to hire investment banks to sell their portfolio companies or take them public upon exit, too, although they tend to favor the banks which brought them the investment in the first place, financed it, and or smothered them with loving attention and juicy new buyout opportunities in the meantime.

So no wonder Blackstone ejected their M&A advisors. Not only can’t they offer the biggest and best paying clients on Wall Street (or anyone else) access to highly profitable leveraged lending, IPOs and equity underwriting, or sales and trading for securities and derivatives (because Blackstone Mère does not offer them), but also the biggest and best paying clients on Wall Street have no interest in hiring them because 1) they don’t value the advice they do have to offer and 2), duh, they work for one of their biggest competitors. I mean, if you could somehow engineer a similar set of constraints for Goldman Sachs’ M&A department, you can bet dollars to donuts the entire group would be camped out on West Street selling pencils before lunchtime.

* * *

Lastly, I have to I disagree with Jeffrey Goldfarb, too. I don’t think this action will start any powerful trends toward consolidating independent M&A advisors like the new PJT-Blackstone Advisory spinoff or even any significant acquisitions of same by larger financial institutions. For one thing, there are only so many synergies and complementarities one can generate in a homogeneous business line like M&A advisory or restructuring before negative returns to scale begin to kick in. At the end of the day, firms like PJT-BA, Moelis, Greenhill, and Evercore are really just a loose collection of fiercely independent, egotistical rainmakers who focus almost entirely on mergers & acquisitions for corporate clients. There isn’t a lot of infrastructure or shared assets to leverage, and there are no complementary business lines like securities underwriting, derivatives structuring, or sales and trading to juice the vig. Managing an advisory boutique is almost exactly like herding a passel of recalcitrant cats, and in my experience, the more the cats, the harder the shepherd’s job becomes.

Similarly, the likelihood a large commercial or foreign bank would snatch up any of these independent advisory shops should be limited by sheer common sense. For one thing, if the acquirer does not already have most of the key complementary underwriting and securities businesses listed above, adding a costly team of pinstriped M&A advisors is going to be an expensive exercise in cultural frustration and no synergy. Adding such capabilities after the fact would be even more expensive and less reversible, since those businesses require real assets, infrastructure, and permanent fixed costs that dwarf those required by the usual M&A department. For another, the history of such acquisitions argues more eloquently than I can against it.

* * *

For Steve Schwarzman, who has not paid noticeable attention to his old advisory business for years and who probably needed to be reminded by Tony James that Blackstone stilled owned it, the motivation for getting rid of the division is clear. He no longer wants or needs to be privy counselor to captains of industry or titans of finance.

It is many years since Steve Schwarzman has considered himself to be—and rightly so—a king in his own right.

Related reading:
Kiel Porter, David Carey, and Devin Banerjee, Blackstone to Spin Off Its Advisory Business With Taubman (Bloomberg, October 10, 2014)
William Alden, Shunning Wall Street Norms, Blackstone to Spin Off Its Advisory Group (DealBook, October 10, 2014)
Jeffrey Goldfarb, Blackstone’s Move Could Set Off a Trend (DealBook, October 10, 2014)
L’État, c’est moi (February 12, 2007) — Steve Schwarzman, Rex
Go West, Young Sheik (September 12, 2007) — Foreign bank acquisitions
Oxymoron (October 13, 2007) – Investment banking “management”
It’s Not the Meat, It’s the Motion (July 15, 2009) — Advisory boutiques

1 There is perhaps an ancillary motivation derived from investment bankers’ unwarranted glamour and notoriety due to their current popular role as B movie villains in our global financial crisis soap opera. But you already knew that.
2 This is not to deny that there are easy returns to scale (to a point) within business lines. Two Guys and a Phone, LLC would likely become much more profitable if it were One Hundred Guys and Several Phones, Inc., if only because they could share resources, support personnel, purchasing synergies, and enhanced marketing and sales generation prospects by looking bigger and hence more reputable to their potential clients, who are often big and diversified themselves. But these cost and revenue synergies often do not obtain between business lines that each have their own separate and different operating structures, client bases, and external market reputations. And past a certain point, scale and diversification can hurt you. The only thing belonging to GigantoBank ever did for me was open the door to an occasional new client who took a meeting because they were afraid GigantoBank would squash them (or more likely revoke their credit line) if they didn’t. A few others refused to meet with me because that is exactly what GigantoBank had already done.

© 2014 The Epicurean Dealmaker. All rights reserved.

Friday, October 3, 2014

Farewell, Ghafla Distraction

What is the airspeed velocity of an unladen swallow?
“Aha! Now we see the violence inherent in the system!”

— Monty Python and the Holy Grail

Yes, it’s true: I’ve left Twitter.

No special reason. All of a part with my reasons for terminating this blog,1 which boil down to being tired of it. I no longer get enough out of the service to merit the near constant immersion and distraction which it seems to elicit from me. I have better uses for my time. And the more substantive readings and links of interest which used to attract me I have sourced otherwise through RSS feeds, so I no longer need to wade through reams of banal tweets on unemployment data, fluctuating bond yields, and the latest outrage du jour of anarcho-social-media-ites to find them.

Of course I am sorry to leave those few friends I have made on Twitter behind. But let’s be frank: there aren’t that many of you, and all of you will get along just fine without me. Besides, if you’re a true friend who’s not a complete mental incompetent, you already know or can find my email address, which remains the same. Those of you who can’t, well, there’s always Kim Kardashian and Justin Bieber. Like your parents, they will always love you and never leave you.

No, really.

1 And no, this does not count as a blog post, except in those pathetic excuses for autofellation some of you frequent elsewhere. My posts have substance. This is a notice, for pete’s sake.

© 2014 The Epicurean Dealmaker. All rights reserved.

Monday, September 29, 2014

TED’s All Time Greatest Hits

They’re all money, honey
The person who experiences greatness must have a feeling for the myth he is in. He must reflect what is projected upon him. And he must have a strong sense of the sardonic. This is what uncouples him from belief in his own pretensions. The sardonic is all that permits him to move within himself. Without this quality, even occasional greatness will destroy a man.

— Frank Herbert, Dune

I have used the preceding epigraph before, as some of you Delightful Readers may recall. It is a versatile and thought-provoking sentiment. Like many quotes and excerpts from Dune, which I contend is one of the greatest science fiction novels ever written, it pleases and intrigues me. It also reminds me—when I am smitten with the unwarranted attention the criminally indiscriminate among you have bestowed upon the thin leavings I whimsically scatter here at unreliable intervals like some verbose will-o-the-wisp—that I am anything but great, or even worthy of attention. I use it sardonically, you see.

I am not without self awareness.

But now I have decided, for the nonce, to abandon you, as I have made clear before. Bummer that, but it cannot be helped. “To everything there is a season,” or some such bullshit. So it strikes me as only fair to post a list of the ten most popular posts I have ever released upon an unsuspecting and undeserving world,1 if only so some people can focus their anger at global injustice and bank overdraft fees on a similarly appalling yet perhaps more accessible target. It is better than reading Slate or Gawker or Jezebel or Guardian pieces, anyway. And they don’t need the page views, I do. I still owe Blogger.com a helluva lot of money for excess pixel consumption, you see.

So enjoy, and please remember to deposit your candy wrappers, empty soda bottles, and previously unexamined prejudices in the handy trash receptacles at the end of the show.

THE CANONICAL CANON, All-Time Canonical Edition:

1) Curriculum Vitae (March 2013) — The canonical career path for young tadpoles to hoary old bullfrogs in my business, corporate finance and M&A. This is what your life will look like if you choose to follow me, children. Warts and all.

2) The Mouth of Sauron (February 2010) — A hit piece, richly deserved, on the fabled former mouthpiece of Goldman Sachs, Lucas van Praag, who is no doubt happily torturing small animals with forks on a leafy Victorian estate in his dotage.

3) The Rules (November 2012) — Read them. Live by them. Pay particular attention to Rule #5.

4) Jane, You Ignorant Slut (May 2011) — The opening salvo in a series of posts about rampant ignorance in the financial press and blogosphere about the nature and mechanics of initial public offerings. This rabbit hole is deep, Alice. Beware.

5) The Invention of Leisure (November 2013) — Junior investment bankers work hard. No matter what people may say or think or do about it, this will not change, and there are very good reasons for that. Not bad reasons, good reasons. See Rule #5.

6) Overheard at 85 Broad Street (June 2008) — An old post in which I eviscerate those gutless weasels at Goldman Sachs who fucked over junior bankers during the Financial Crisis in a particularly cowardly and reprehensible way. I can neither confirm nor deny rumors that Goldman moved its global headquarters to 200 West Street solely to escape the historical opprobrium of this post.

7) Go Ask Alice (September 2013) — The bookend to the series on IPOs, begun with 4) above. Read these two, and the intervening posts, and you will know more about IPOs than most investment bankers and all financial pundits.

8) A Fine Disregard for the Rules (January 2014) — More reasons why junior investment bankers work like dogs and always will, no matter how many foosball tables and papaya soy lattes Google and Facebook try to tempt them with.

9) To Catch a Thief (February 2009) — Do investment bank executives strike you as, well, a little odd? I suspect you are right.

10) Where Did He Learn to Negotiate Like That? (August 2014) — Investment bankers, by training and inclination, tend to be much better negotiators than many of their clients. Occasionally this works to the client’s disadvantage.

* * *

Since these posts are ranked here, as is my custom, simply by aggregate historical page views as collected by Google Analytics, some of you may notice a recency bias, as the number of readers coming to these pages has accreted over time like barnacles on the hull of a poorly maintained ocean freighter. You will also notice a narrower range of topics and treatments than your local bartender may have informed you I offer, which is related to said recency. Those masochists among you who would like to explore both deeper in time and more broadly across my variegated oeuvre I would encourage to start in the archives and use my idiosyncratic keywords and Blogger’s search function liberally. There is nothing for it but to dive in, headfirst, and try to stay afloat on my sea of words, just as a tyro investment banker plunges into her apprenticeship of fire.

The metaphors are deep, O Dearly Beloved, and mixed. Welcome to my world.

Related reading:
Table of Contents — the archives
Topics Addressed in These Pages — idiosyncratic keywords

1 I exclude, as is my custom, generic results like this blog’s home page, recommended reading, outdated personal information, introductory blather, and my curated archives. I suspect you can have no objection.

© 2014 The Epicurean Dealmaker. All rights reserved.

Saturday, September 20, 2014

Oop. Time, She’s Up

Just an old fossil
“I am old, Gandalf. I don’t look it, but I am beginning to feel it in my heart of hearts. Well-preserved indeed! Why, I feel all thin, sort of stretched, if you know what I mean: like butter that has been scraped over too much bread. That can’t be right. I need a change, or something.”

― J.R.R. Tolkien, The Lord of the Rings

When I launched this blog seven and three-quarters years ago, O Dearly Beloved, my first post incorporated the following mission statement:
I have started this blog to comment on what I consider to be a fascinating part of the global economy: the global market for M&A and its various inhabitants, participants, and miscreants. Hopefully I will be able to relate some interesting anecdotes, a few enlightening opinions, and a couple of amusing stories that will shed a little more light (or a little more laughter) on what remains for many a murky area best left to investment bankers, corporate lawyers, and other such terrifying bogeymen.
Five hundred and sixty-six published posts later, more or less, plus a lumber room of unpublished fragments, ruminations, and provocations, I think I am ready to declare victory and move on. This is not necessarily because even I believe that I have achieved victory, mind you. That is for you Lovely People and the sub-sub-librarians of internet history to judge. But one of the advantages of running a blogsite of which you are the sole, unimpeachable authority, author, and editor rolled into one is the ability to make such unilateral declarations without fear of pesky contradiction from the peanut gallery. (I have not made it a policy here to prevent comments for nothing, children. If you object I can direct you to a convenient pile of nearby sand which needs pounding.)

Of course those of you who have made an intermittent study, intentional or not, of my ramblings on this site will be aware that my output has both exceeded and failed to satisfy my stated mission of explaining the market for corporate mergers & acquisitions. The lion’s share of this mission creep (or evasion, if you will), I must put down to my lack of discipline: I have used this platform to hold forth on all sorts of topics and sundry, many of which fall far afield from the cloistered halls of buying, selling, and financing companies, which is my primary trade. I have addressed mildly cognate fields like private equity, Corporate America, and the history, structure, and pay of the investment banking industry; more tenuously related areas including hedge funds, capital markets, and financial regulation; and wildly off-topic digressions such as higher education, philosophy, and identity in the age of Facebook and the NSA. I have indulged my fancy for humor without regard for its funniness to anyone else, and I have waded into culture and art criticism without shame or regard for my lack of training or expertise therein. I have posted pictures and poems that appealed to me, for no other reason than I could.

In other words, I have written about what interests me, in addition to that much narrower and shallower range of topics to which I legitimately claim any expertise. The curated list of my more prominent posts runs to many pixels and reveals the breadth of my work. I remain unapologetic about this. This site is a personal blog, not a public service. Those of you who disagree with my choices are welcome to join the protestors from the first paragraph at the nearby mound of silica, etc., etc.

* * *

I was lucky to start blogging when I did. Financial markets had reached a peak of silliness which offered rich fodder to a financially literate cynic such as myself. Soon, the global financial crisis elbowed aside these more pedestrian concerns to offer a rich and exciting topic for me to both demonstrate my naturally firmer grasp on markets and the financial industry than the legions of panicky and underinformed journalists and pundits who were scrambling to understand and report it and also learn more about the crisis’s players, issues, and concerns than I had theretofore known myself. While I claim no particular merit for having done so, I take pride in contributing some measure of rational, grounded knowledge and facts to a society-wide conversation about the Panic which was badly in need of them. I even tried to contribute more serious thinking to the reform of financial regulation in this context, but sadly that seed fell on stony ground.

Subsequently, I think I have contributed some things of use to the broader understanding of investment banking and financial markets, including reality-based commentary on initial public offerings, illumination of the ways and byways of careers in my industry, and a little insight into the plight and prospect of women in high powered careers like mine. Hopefully these small contributions have added something of value to the public understanding and hence social weal. If so, I am glad. If not, well, you all got what you paid for.

But now I have reached a pass where I find it increasingly difficult to maintain any sort of regular posting on these pages. Most of what I have to say about things I know I have already said, often more than once. I have come to realize I will never convince those who believe in their bones that investment banking and financial markets are useless, evil, or a social liability rather than a boon. People who use the word “bankster” unreflectively and unironically are not now and never will be interested in what I have to say. People who have a more nuanced understanding, or who continue to form their opinions on the matter, have many more sources today than they used to to call upon, and a much broader and deeper understanding of these issues in the press. I hope I have contributed in some small way to this education. Unless Blogger.com sinks beneath the waves, people should always be able to find my blatherings on these topics gathering dust at this location for handy reference anyway.

I expect I will continue to maintain this site in some small way, perhaps adding a post here and there to the topic listing at the Table of Contents and maybe even doing a final and/or comprehensive post of Greatest Hits. But I do not anticipate blogging here regularly any more. I have reached the end of the interests and expanded mission which drove me to launch myself into cyberspace in the first place. Now I am most interested in topics where I am a student and a learner, not a master, and I want to spend the not inconsiderable time I have devoted in the past to explaining financial arcana and beating back the ignorance of the unfair and unjust here to reading and thinking about others’ expertise and ideas instead.

* * *

If I find I have something interesting to say, never fear, O Faithful and Long-Disappointed Readers, I will probably say it here. Those of you who know me via this opinion emporium probably have little doubt of that. I am the sort of person in fact whom it is almost impossible to shut up. It just is unlikely to be a regular affair, and this site is likely to sink into desuetude and decay as the years lengthen. Whether I decide to pop up in some other form, at some other place, I have yet to decide.

If I do, I’ll be sure to drop you a postcard. Cheerio.

Related reading:
Fragments (February 26, 2010)
Table of Contents (February 16, 2013 and passim)

© 2014 The Epicurean Dealmaker. All rights reserved.

Sunday, September 14, 2014

Some Work of Noble Note May Yet Be Done

What is the price and cost of duty? What is its pleasure?
We are not now that strength which in old days
Moved earth and heaven, that which we are, we are,
One equal temper of heroic hearts,
Made weak by time and fate, but strong in will
To strive, to seek, to find, and not to yield.


— Alfred Lord Tennyson, “Ulysses”

Ever since the release of Dr. No in 1962, the James Bond 007 films have acted as a touchstone and running commentary on popular culture and society. For over half a century, a parade of different Bonds, Bond Girls, and increasingly over the top villains have offered escapist fantasies of varying implausibility and ridiculousness which have served, inter alia, as travel brochures, fashion statements, and advertisements for the benefits, drawbacks, and terrors of technological progress. They have done this, for the most part, not because it was their makers’ purpose (or even within their power) to critique society, but rather because they were intended to be hip, with it, and relevant, even at the inevitable expense of any seriousness or credibility. (Roger Moore, anyone?) With various degrees of success, these pop confections have held a mirror up to society. It is no wonder not everybody likes what they see.

These thoughts were inspired by film critic A.O. Scott’s interesting essay on the death of adulthood in American culture, which seems to be making the rounds of the culturesphere. He says many things, but his major point seems to be that popular culture, moviemaking preeminent within it, has elevated a strain of anti-adulthood and fixation on youth long dominant in American culture to the forefront of everything we see. I am not qualified to judge the correctness of his claim, but it certainly does seem to me the flight from responsibility and adulthood and the joys and tribulations of perpetual adolescence have become a leading subtext or topic for a very large number of popular entertainments nowadays. In particular, this cultural conversation seems to be focused on men and boys and their refusal to grow up.

Interestingly, upon reading Scott’s essay, my thoughts turned immediately to the most recent film in the Bond series, Skyfall. It occurred to me this movie can be read as providing a very interesting commentary on the issues of growing up, responsibility, and adulthood for a man nowadays, even if—or perhaps because—it is wrapped up in a popular escapist spy thriller. I claim no special cultural profundity for the film, nor no searing insight for the filmmakers or screenwriters, but I think the mirror which this particular thriller holds up to our current zeitgeist is pretty revealing. Even if the cultural critique I read within it was unconscious, or only semi-intentional, that does not vitiate its insight or force. Perhaps it enhances it. You Delightful Readers can judge for yourselves. If Stanley Cavell can find deep commentary on Hamlet embedded in Alfred Hitchcock’s North by Northwest, I can certainly tease a bildungsroman out of a Bond film. It’s my blog, anyway.

* * *

I will not tax your patience by relating the plot or other details of the film which you can discover yourself if you like. Nor will I spare you any spoilers. If you have not seen it already, there is no plot element I can reveal that will diminish your appreciation of the movie as cultural critique. In my experience, anyway, it is a measure of the quality of a story that you are willing to reread or rewatch it even when you know how it turns out. Skyfall is that good a movie.

The key plot points I would draw your attention to are as follows:

  • At the beginning of the film, Bond is accidentally shot by his competent, no-nonsense assistant while attempting to recover a stolen data file from the top of a train barreling toward a tunnel of no return (cue Alfred Hitchcock and Sigmund Freud). Bond’s assistant, who happens to be black and female, shoots him on the explicit orders of their boss at British intelligence, “M,” who, while white and old, also happens to be female (Judi Dench). Bond, by the way, is an orphan who has a simultaneously fraught and close relationship with M which a casual observer could mistake for a mother–son dynamic.
  • After plunging to his apparent death in deep water (cue Carl Jung, opening credits, and Adele’s theme song), we later discover Bond is alive after all, although he appears to be hiding from M and MI-6 in an exotic backwater and spending his time in self-destructive drinking, meaningless sex, and taunting dangerous arachnids for thrills and money.
  • Bond comes back home to mother M when he hears she and MI-6 are under attack by a mysterious hacker who can penetrate British intelligence’s defenses at will. M displays no regret, casually informs Bond she has sold his home and all his belongings, and puts him into a crash course to get fit for active duty again, at which he struggles painfully. Nice homecoming.
  • Bond tracks the mysterious hacker through various exotic locales and the beds of one or two expendable women to an abandoned island off the China coast, where he discovers a platinum blond Javier Bardem who minces and lisps and puts the moves on our trussed up spy. Bardem, it seems, is Bond’s evil twin, who is pissed at M for betraying him to the Chinese. He has channeled his anger into a worldwide empire of computer intelligence and manipulation, which he sells to the highest bidder. Strangely, though, this evil computer genius uses data screens that look like video games.
  • After more plot machinations and an unsuccessful attempt on M’s life by Bardem (for an evil computer genius, he’s pretty lame with a gun), Bond flees with M to his ancient family home in Scotland, Skyfall, where he acquired what an MI-6 psychologist called his “pathological rejection of authority due to unresolved childhood trauma.” Bond himself tells M they’re going “into the past.” For transportation, they use Sean Connery–Bond’s Aston Martin DB5 from 1964’s Goldfinger. Into the past, indeed.
  • An epic battle ensues at Skyfall, in which Bond, M, and Bond’s old gamekeeper and surrogate father battle Bardem and his small army, resulting in the destruction of Skyfall (which Bond hates), the Aston Martin DB5 (which only seems to mildly irritate Bond), and Bardem’s army. Bardem tracks a wounded M to a chapel where, while trying to persuade her to shoot both herself and him in the head to end their misery, Bond literally stabs Bardem in the back with a large hunting knife. So much for homosexual tension with your evil twin.
  • Finally, after blessing Bond with her approval, M dies.
* * *

Now of course everyone who watches Skyfall knows all about James Bond. (All Bond movies assume it.) He is a charming, ruthless killer, a master manipulator with no empathy who treats friendly and hostile women alike like Kleenex and enemies like target practice. He is unmarried and childless, a man with no duties or responsibilities other than his job, which he often does grudgingly and against orders. Come what may, he always wins, usually punctuating his triumph with a cynical joke. As a cultural symbol of the last half century, James Bond is Peter Pan with a gun. For a British character he is as American as they come.

And yet in Skyfall he is betrayed and (symbolically) killed by women (including his mother), he falls into adolescent irresponsibility and self destruction, he is blocked and belittled by the genius avatars of today’s high technology (one of whom is gay or bisexual and the other is so young he still has spots), and he struggles not very successfully against physical and intellectual decrepitude. What more comprehensive list of challenges facing modern American man can one compile? What greater list of fears and blocks to maturity torture the brains of today’s man: emasculation, obsolescence, irrelevance, sexual confusion, self-indulgence, failure, age?

But Skyfall’s James Bond does not remain on the beach in India to sulk, boozing for breakfast and daring scorpions to sting him. He does not smoke pot and play Parcheesi with his stoner 30-something friends while the world burns or skip dates with beautiful women far out of his class to rearrange his vintage comic book collection. He is no Marvel superhero or genetically enhanced super soldier who can pretend to be invincible. This James Bond is the most vincible hero we have seen. And yet he picks himself up painfully, dusts himself off, and throws himself back into a game he is not sure—we are not sure—he can win, because it is his duty.1 This is the opposite of the flight from adulthood. This is its embrace: the embrace of duty and responsibility. If there is a bubblegum escapist fantasy thriller which offers a better critique of the flight from adulthood—yet does not shy away from depicting how difficult and costly adulthood is—than this, I do not know what it is.

* * *

At one point, as Bardem’s villain bears down on M’s public hearing to kill her and Bond sprints through the streets of Whitehall to stop him, Judi Dench–M recites the conclusion from Alfred Lord Tennyson’s poem “Ulysses” at the top of this post. The effect is inspirational, as we fully understand by now the effort and will it requires for Bond to push his aged, broken-down body through the streets to rescue both the head of his service and the only woman he has considered his mother for his entire adult life.

And yet Bond is not Tennyson’s Ulysses, a selfish, vain old man who wants to abandon his aged wife—who waited patiently for him for twenty years of wandering—his dutiful son, and his own people, to fling himself onto the wine dark sea once more in search of glory and adventure. No, Bond is a soldier, a dutiful son who dons his buckler and sword to wade again and again into the blood and mud of the battlefield, risking life and limb for the country which is his only family and his only allegiance. At the end of the movie, Mallory–M welcomes him into his new office—the original Bernard Lee–M’s office, down to the paneling, soundproofed door, and paintings on the wall; a fine, full circle the filmmakers have crafted for us2—and tells him as he tosses a new mission brief onto the desk, “So, 007, lots to be done. Are you ready to get back to work?”

Bond replies with a smile, “With pleasure, M. With pleasure.”

That is adulthood, children. That is what it means to be a man.

Related reading:
A.O. Scott, The Death of Adulthood in American Culture (The New York Times, September 11, 2014)

1 I am not overlooking the element of revenge in Bond’s motivation; it is undoubtedly there. But this is just to say that Bond’s character’s motivations are multifarious and complex, as they are in real life. This makes Skyfall a better film, if a more complicated and ambiguous one in many respects.
2 Note how, having reset the location of M’s office back to its setting from the very first film of the series, the filmmakers have also given enough backstory and proof of Mallory’s personal courage and toughness to justify his position in M’s chair. No longer just a fat, slightly ridiculous old man behind a desk, M’s role as leader and father to James Bond has been justified to us and to Bond. This little bit of the patriarchy, at least, makes sense again.

© 2014 The Epicurean Dealmaker. All rights reserved.